2026-11-06 Author : ZCS
PopID biometric payments do not charge money from a face. PopID uses an opt-in face match to identify an enrolled customer and retrieve an associated profile; the merchant's payment stack then submits a linked payment credential for authorization. The broader palm biometrics identity guide explains how a biometric template can represent identity. This article follows the additional steps required to turn identification into loyalty check-in and payment.
The easiest way to understand pay-by-face is to separate the visible gesture from the services behind it.
PopID biometric payments represent an enrolled biometric checkout category in which PopID performs consent-based face verification, a merchant application connects the verified profile to loyalty or ordering data, and a payment provider processes a linked credential. A camera captures the customer, but the camera alone neither stores value nor authorizes the transaction.
That division of work explains why a two-second customer gesture can depend on several systems that remain invisible at the counter.
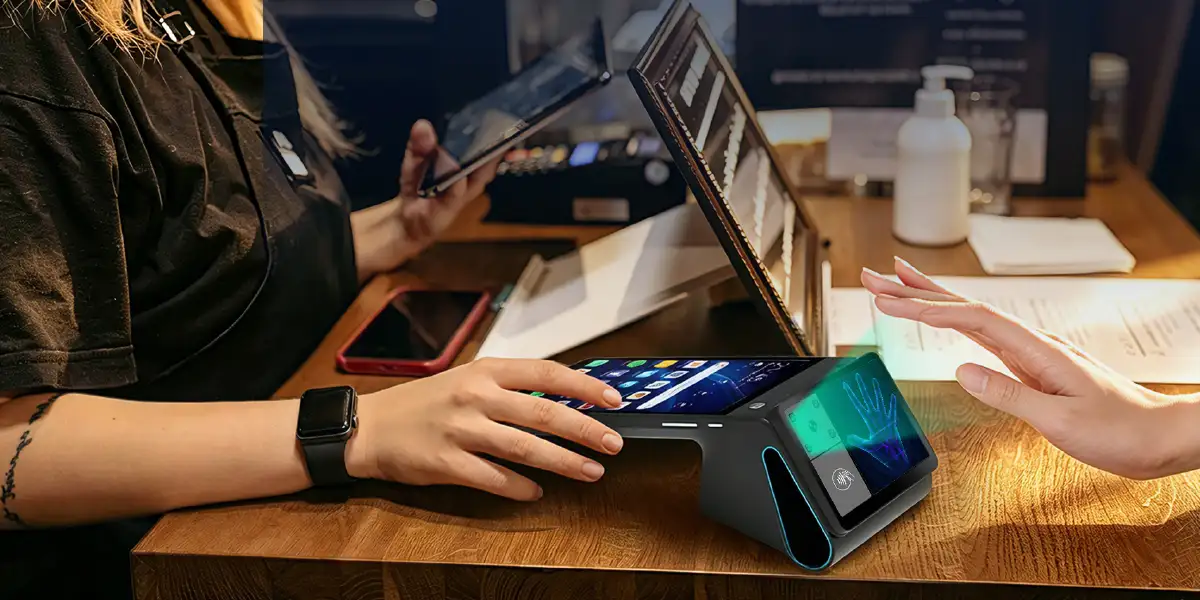
PopID biometric payments are an account-based checkout service that uses face verification as the customer's identifier. A user enrolls, creates a protected biometric reference, and can add payment information. At a participating merchant, the user actively chooses face recognition, the service attempts a match, and the matched account can supply the information required for loyalty or payment.
PopID's current explanation describes four broad actions: sign up with a face or palm image, choose recognition at an enabled business, let the PopID cloud compare the new capture with the stored key, and use the resulting identity for supported services. The PopID service overview also says users must press an on-screen button or tell the cashier before recognition begins.
The biometric match is therefore an identity result, not a complete card transaction. A successful result can tell a participating application which PopID profile is present. The merchant still needs an order total, an eligible payment method, a route to J.P. Morgan Payments or another processor, and an authorization response.
The visible flow may feel like “look, confirm, paid,” but the system performs several distinct jobs:
PopID and J.P. Morgan occupy different layers of the same checkout. PopID supplies the biometric enrollment and matching relationship. J.P. Morgan Payments can supply merchant payment processing, acquiring infrastructure and transaction services. The merchant controls the sale, customer experience and store procedures.
| Participant | Primary role | What the participant does not do by itself |
|---|---|---|
| Customer | Enrolls, links an eligible payment method and chooses biometric recognition | A face alone does not hold funds or approve every transaction automatically |
| PopID | Creates or manages the biometric reference, performs matching and returns an identity result | A match is not the issuer's payment authorization |
| Merchant and POS software | Builds the order, displays the amount, invokes loyalty and payment functions, and records the result | A POS order does not prove the customer was matched or the payment approved |
| J.P. Morgan Payments | Processes the payment for supported merchant deployments and returns transaction status | Processing does not replace PopID enrollment or the merchant's loyalty database |
| Card issuer or account provider | Approves or declines the submitted transaction under account and risk rules | The issuer does not operate the store camera or decide the loyalty reward |
J.P. Morgan Payments described this division in its August 6, 2024 expanded partnership announcement. The official PopID collaboration notice states that PopID converts an enrollment photo into a template, stores it in encrypted form in the PopID cloud, and informs the merchant of a match result. The same announcement identifies J.P. Morgan Payments as the payment-processing partner for participating deployments.
The 2024 announcement is evidence of a partnership and U.S. pilot expansion, not proof that every J.P. Morgan merchant can activate PopID automatically. Merchant participation, supported software, approved devices, commercial agreements and operational readiness still define availability.
Enrollment creates the relationship that later makes pay-by-face possible. A store camera cannot infer which card or loyalty account belongs to an unknown shopper. The user must first create or connect a profile under the applicable enrollment terms.
PopID enrollment begins with an explicit customer action. The user supplies account information and a facial image through a supported sign-up experience. The service converts biometric features into a reference used for later matching.
The distinction between an image and a template matters, but it does not eliminate privacy obligations. A merchant should document which organization receives the original image, whether that image is retained, how the derived template is protected, how long records remain, and how a person can revoke consent.
A loyalty link allows face verification to replace a phone-number lookup, QR code or membership-card scan. After the match, the merchant application can retrieve the customer's rewards balance, past order options or eligible offers according to the merchant's program rules.
The palm-vein membership and loyalty guide describes the same account-linking principle with a different biometric. Both face and palm systems need an enrolled identifier connected to an existing customer record; neither biometric creates the loyalty program itself.
Payment requires a separate funding relationship. The customer can link an eligible card or another supported account during enrollment. The payment information must be validated and protected under the relevant service design before it can be used at checkout.
PopID's Miami Grand Prix enrollment page described a three-step sequence in 2024: create a PopID account, add a credit or debit card, and use biometrics at the participating shop. The page also made the responsibility boundary visible by labeling PopID as the technology provider and J.P. Morgan Payments as the processor.
The practical lesson is direct: the face points to an account, while the linked credential identifies where the payment request should go. Removing the physical card from the customer's hand does not remove the card account or payment-processing chain.
A pay-by-face transaction starts with an ordinary sale. The POS records items or services and calculates an amount before the biometric function becomes relevant. Face recognition should not create or change the order without the merchant application showing the customer what will be charged.
The operational sequence can be represented as follows:
| Stage | System action | Customer-visible result |
|---|---|---|
| 1. Order creation | POS records items, tax, discounts and total | Customer sees the proposed purchase amount |
| 2. Biometric opt-in | Customer selects face payment or asks the cashier to start it | Camera is activated for the requested transaction |
| 3. Capture | Camera obtains a live face sample under the service's capture rules | Customer looks at the designated display or camera |
| 4. Matching | PopID compares the sample with the enrolled reference | System reports a match, no match or retry condition |
| 5. Profile retrieval | Merchant application requests permitted loyalty and payment data | Rewards or account choices may appear |
| 6. Customer confirmation | Checkout confirms the total and applicable payment method | Customer approves the purchase under the configured flow |
| 7. Payment processing | Linked credential is submitted through the merchant's payment route | Approved, declined or pending result returns |
| 8. Recording | POS stores receipt, order, processor reference and loyalty outcome | Customer receives confirmation or a fallback prompt |
The separation between matching and authorization is the central technical point.
A PopID face match confirms that the captured customer corresponds to an enrolled PopID profile under the service's matching rules. J.P. Morgan payment processing submits the selected credential and amount through the merchant's acquiring path. The issuer can still approve or decline the transaction after a successful biometric match.
That means a green recognition result should never be treated as proof that money moved. Store software must wait for the payment response and preserve the processor reference needed for receipts, refunds and reconciliation.
Loyalty identification and payment do not have to occur at the same moment. A restaurant can recognize a member near the start of ordering, display eligible rewards, and later ask the customer to confirm payment. Another merchant can use the biometric only at the final tender screen.
This timing choice changes the customer experience and the privacy notice. Recognition used for personalization may occur earlier than recognition used only to authorize a purchase. Merchants should avoid treating consent to pay as automatic consent for broader profiling or personalized recommendations.
A successful match can still lead to a declined payment. The linked card may be expired, the issuer may reject the amount, the account may lack available funds, or a risk rule may require another action. The customer then needs a clear route to another payment method.
The POS should display separate statuses such as “identity matched,” “payment submitted,” “approved,” “declined” and “status unknown.” Combining these states into a single spinner makes duplicate attempts and customer disputes harder to resolve.
J.P. Morgan Paypad and Pinpad are payment terminals, whereas PopID is the biometric identity and checkout service discussed in the partnership. The hardware can present payment choices and capture supported interactions, but the terminal does not remove the need for enrollment, matching services or merchant integration.
J.P. Morgan Payments introduced Paypad and Pinpad at NRF in January 2025. The Paypad and Pinpad product explanation says the Android-based devices were designed to accept chip, contactless, swipe, QR and biometric methods. Paypad was described as a larger portable or docked touchscreen device, while Pinpad was described as a compact unit with a physical keypad.
The 2025 terminal announcement should not be rewritten as a universal production claim. J.P. Morgan's page says Paypad would be piloted with a subset of enterprise clients and includes a notice that future hardware and biometric capabilities were under development, with features and timelines subject to change.
The chronology is therefore:
These dates show an evolving program, not one single nationwide launch event.
A camera only supplies image input. Deployable PopID biometric payments also need account enrollment, consent management, protected template storage, matching, loyalty integration, a linked payment credential, acquiring, transaction-status handling and customer support.
| Required layer | Question the merchant must answer |
|---|---|
| Camera and placement | Can the device capture a usable, intentional sample at the lane, kiosk or drive-thru? |
| Biometric software | Which provider performs matching, presentation-attack checks and confidence decisions? |
| Enrollment | Where does a customer sign up, link accounts, update details and withdraw? |
| Loyalty integration | Which customer fields and rewards can the biometric result retrieve? |
| Payment binding | Which card, wallet or account can be selected after a match? |
| Payment acceptance | Which acquirer and processor submit the transaction and return status? |
| POS integration | How are amount, discounts, tender choice, receipt and refund references synchronized? |
| Operations | Who handles no-match, decline, network outage, mistaken account and deletion requests? |
A front-facing camera on an Android POS does not prove PopID compatibility. Compatibility requires the provider's supported software, device approval, merchant onboarding and payment integration. A generic camera specification cannot establish any of those conditions.
The same warning applies across biometric modalities. A palm sensor does not automatically connect to a card network, and a face camera does not automatically connect to PopID. The Mastercard biometric payments guide makes a related distinction between a biometric used locally to unlock a device passkey and a biometric captured by store infrastructure.
Face and palm payment can follow the same account-and-payment architecture while using different capture hardware. Both systems normally require enrollment, a protected biometric reference, a live sample, a match decision and a linked payment credential. The main workflow difference is how the customer presents the biometric.
| Deployment question | Face verification | Palm verification |
|---|---|---|
| Capture device | Camera positioned for a usable facial image | Palm-facing optical or near-infrared sensor |
| Customer action | Look toward the designated camera after opting in | Present a hand above or near the reader |
| Environmental sensitivity | Camera angle, lighting, face coverings and crowd positioning | Hand position, scan distance and sensor environment |
| Intent signal | Needs a clear opt-in action to avoid passive recognition concerns | Presentation of a hand can provide a more visible deliberate gesture |
| Familiarity | Similar to face unlock, but store-side capture is a different data relationship | Less common for many shoppers and may require brief guidance |
| Payment dependency | Still needs account binding and processor authorization | Still needs account binding and processor authorization |
ZCS approaches biometric checkout as an integrator-configurable hardware layer rather than a closed pay-by-face service. The ZCS Z108P palm vein recognition terminal combines palm-vein capture with optional face recognition on an Android terminal, giving a project team two possible identity inputs without defining the payment account, acquirer or customer-enrollment service.
| ZCS hardware capability | What an integrator can build around it | What the capability does not establish |
|---|---|---|
| Palm-vein recognition | Deliberate hand-presentation workflows for identity, attendance, loyalty or payment authentication | Automatic connection to a card network or acquiring service |
| Optional face recognition | Camera-based identity verification within a custom Android application | PopID enrollment, template portability or PopID certification |
| Android platform and optional QR/NFC functions | A combined customer interface for identity and supported transaction methods | Approval by J.P. Morgan Payments or any specific processor |
| Server-side matching architecture | Connection to an integrator's enrolled identity database and business rules | A complete consent, privacy, refund or dispute process |
The correct ZCS deployment question is therefore “what service stack will the integrator connect to the terminal?” A Z108P project still needs consent capture, enrollment, template governance, loyalty or account mapping, payment-credential protection, processor approval and fallback checkout. ZCS face recognition and palm vein technology can provide the capture and terminal layer, but they do not replace PopID's service role or J.P. Morgan's processing role.
No public evidence in the cited materials supports a fair PopID-versus-palm accuracy ranking. Accuracy depends on the exact sensor, software version, matching threshold, population, lighting or positioning, liveness controls and test method. Results from different vendors or environments cannot be treated as one controlled comparison.
The more useful decision is operational. Face capture can fit kiosks, drive-thru lanes and counters already designed around a customer-facing camera. Palm capture can make the act of presenting a biometric more explicit. The palm vein, fingerprint and face comparison explores modality differences, but payment projects must add credential binding and acquiring to that identity analysis.
Merchant deployment succeeds or fails at the system boundaries around the match. A fast face result has limited value when the POS cannot apply rewards correctly, distinguish a decline from a timeout, or locate the processor reference for a refund.
The POS must send a definite order and amount into the payment flow. Kiosks, cashier lanes and drive-thru systems may start recognition at different points, but each implementation must prevent the customer profile from becoming attached to the wrong open order.
The integration should define session timeouts, lane identifiers, retry rules and account clearing after each customer. A prior customer's loyalty profile must disappear before the next sale begins.
The loyalty service should receive only the identity and permissions needed for the requested task. A face match may support rewards lookup without giving every store application unrestricted access to biometric data. The integration should separate the match result from the underlying template.
Merchants should also decide whether recognition triggers personalized recommendations. That use goes beyond simple payment authentication and may require a separate explanation or customer choice.
Refunds depend on transaction records, not another face scan alone. Staff need the original order, processor reference, amount and refund permissions. A matched customer profile can assist lookup, but the payment system must follow the merchant's approved refund process.
Reversals and uncertain transactions need equal attention. A network interruption after submission can leave the POS unsure whether the processor received the request. The store should check the authoritative payment status before trying the linked credential again.
Support ownership must be divided before launch. The camera vendor may handle hardware failure, PopID may handle enrollment or matching, the POS provider may handle order integration, and J.P. Morgan Payments may handle processing issues. Staff need one escalation map that identifies the correct owner from the observed failure.
Consent must be understandable at enrollment and visible at use. A customer should know that a store-side camera is connecting to a biometric service, not merely taking the same local action used to unlock a personal phone.
PopID says customers choose recognition by using an on-screen control or notifying the cashier. PopID also provides a current privacy-policy link and describes opt-out controls. Merchants still need to confirm which terms apply in the deployment's jurisdiction and which organization responds to access or deletion requests.
The security review should cover at least:
Encryption is one control, not the complete answer. PopID's published security page states that data passing through its servers is encrypted using FIPS 140-2 validated security modules and describes device-management and monitoring controls. A merchant assessment should still examine the specific contract, architecture, retention terms and incident responsibilities for the proposed deployment.
Pay-by-face has the strongest operational case where customers return often and queues have measurable cost. Repeated visits allow one enrollment to produce value across many transactions. Restaurants, stadiums, campuses and membership venues can also connect identification with loyalty or entry rather than relying on payment convenience alone.
Good candidate environments share several traits:
Low-frequency retail is a harder adoption environment. A visitor who may never return has little reason to create a new biometric account for one purchase. Enrollment friction, privacy questions and support cost can outweigh seconds saved at the counter.
The merchant should measure adoption rather than assume it. Useful pilot metrics include enrollment completion, repeat biometric use, match retries, checkout duration, payment declines, fallback rate, loyalty identification rate, support contacts and deletion requests. Vendor-reported speed or ticket-size claims should not replace a store's own controlled baseline.
A pilot should prove the full transaction and recovery path before expansion. Camera performance is only one test item.
No. A facial template is used for biometric matching, not as a financial account. PopID biometric payments need a linked card, bank account or other supported payment method from which the transaction can be processed.
J.P. Morgan Payments can provide payment processing and acquiring services for participating merchant deployments. PopID performs the biometric identity function, while the merchant's POS creates the sale and an issuer or account provider makes the final approval decision.
One capture can support both functions only when the merchant has integrated both services and the customer has linked the relevant accounts. Loyalty lookup and payment authorization remain separate system actions even when the interface combines them.
No. Paypad is a J.P. Morgan payment terminal, while PopID supplies biometric identity and checkout services used in the partnership described in 2024. A terminal still needs supported applications, enrollment and merchant configuration.
No. A camera does not establish PopID compatibility. The device, software, merchant account, biometric service and payment integration must all be supported for the intended deployment.
The available experience depends on the participating merchant and deployment. Biometric identity can support payment, loyalty check-in or both, but each function requires the corresponding account relationship and merchant integration.
The merchant should treat recognition and payment as separate statuses. Staff can offer another payment method after the POS confirms that the linked-credential transaction was declined and no uncertain authorization remains.
The cited PopID and J.P. Morgan materials do not provide a controlled face-versus-palm accuracy comparison. A fair test would require the same population, environment, threshold, liveness controls and error definitions, so a universal ranking would be unsupported.
PopID and J.P. Morgan make pay-by-face possible by connecting two systems, not by turning a face into money. PopID enrolls and matches a consenting customer. The merchant uses that result for loyalty or account retrieval. J.P. Morgan Payments can process the linked credential through the merchant's payment path, after which the issuer or account provider returns the transaction decision.
The 2024 partnership and the 2025 Paypad/Pinpad announcement should also remain separate in any explanation. The first documented PopID-powered biometric checkout and pilot expansion. The second introduced proprietary J.P. Morgan terminal hardware with several accepted payment methods and future biometric capabilities subject to published limitations.
The deployment test is therefore broader than camera quality. A workable pay-by-face system needs deliberate consent, reliable enrollment, correct loyalty binding, protected payment credentials, clear authorization status, refund and reversal handling, non-biometric fallback and support ownership across every provider involved.




 Home
 Which Ingenico Move 5000 Alternatives Can Preserve Your Acquirer and POS Integration?

