
2026-11-17 Author : ZCS
Payment processing turns a checkout request into an approved payment, a completed financial record and a merchant payout. A customer sees one card tap or online confirmation, but several systems exchange information before the money reaches the merchant’s bank.
The category is defined by two connected flows.
Payment processing carries transaction data between a merchant, processor, acquirer, card network and issuer, then uses completed records to settle financial obligations. Authorization confirms whether checkout can proceed. Capture, clearing, settlement and merchant payout complete the later record and funding stages.
That distinction explains why a terminal can display “approved” while the merchant’s bank balance remains unchanged.
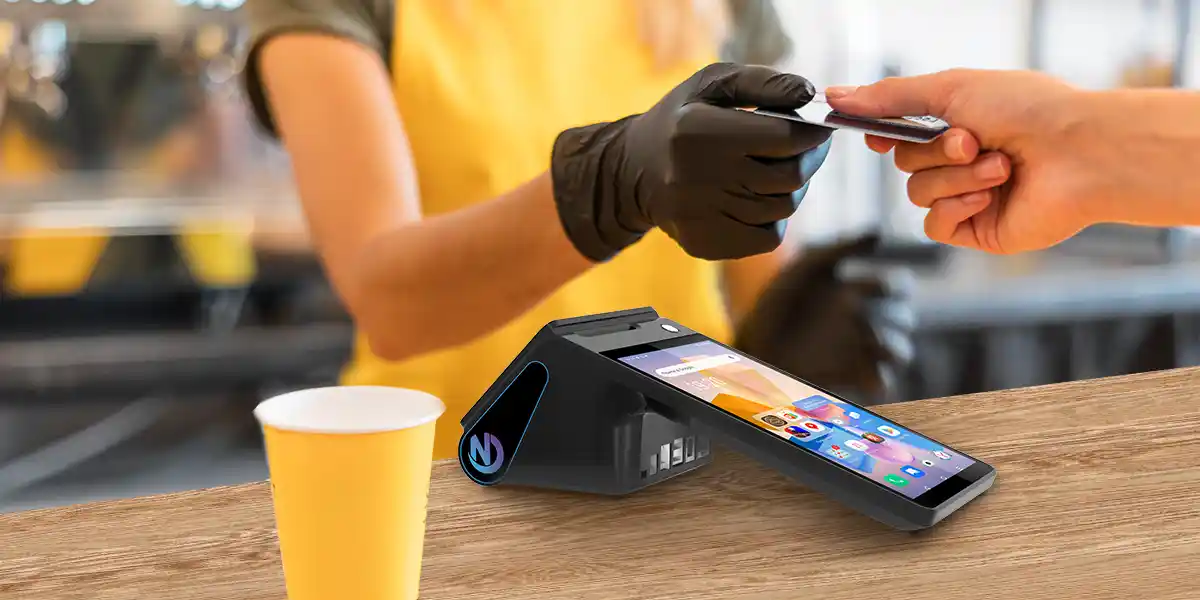
Payment processing is the system that accepts a payment request, routes it for approval, records the completed transaction and funds the merchant. It covers both the real-time checkout decision and the later movement of financial records and money.
Card payment processing has five main stages:
These stages can happen through one cashier action. A standard retail sale often authorizes and captures the payment without asking the cashier to press a second button. The records still remain distinct.
Visa’s explanation of credit card processing stages separates authorization, clearing and settlement while identifying the cardholder, merchant, issuer and acquirer. This structure remains useful when a gateway, processor or payment facilitator adds another service layer.
Payment processing is broader than a POS terminal. The POS creates the order, the terminal or payment page collects the credential, the processor routes messages, and the issuer makes the authorization decision.
No single participant controls the entire payment. Each party owns a specific decision, message or financial relationship.
| Participant | Main role |
|---|---|
| Cardholder | Presents a card or wallet and completes required verification |
| Merchant | Creates the order, amount and fulfilment obligation |
| Payment gateway | Secures and transmits online or application payment data |
| Payment processor | Formats, routes and records transaction messages |
| Acquirer | Manages the merchant-side card acceptance relationship |
| Card network | Connects acquirers and issuers under network rules |
| Issuer | Manages the cardholder account and approves or declines authorization |
| Payment facilitator | Onboards and manages merchants through a sponsored acquiring arrangement |
The issuer controls the card-account authorization decision. A merchant or processor can block a transaction through its own fraud rules, but it cannot approve funds on behalf of the customer’s bank.
The acquirer controls the merchant-side financial relationship. The acquirer receives transactions, supports settlement and works with the provider that sends payouts to the merchant.
The card network connects the issuer and acquirer. Visa and Mastercard route network messages and support clearing and settlement; they do not operate the merchant’s sales system or business bank account.
Visa Acceptance Solutions distinguishes the gateway and processor roles: the gateway collects and protects checkout information, while processing services connect payment messages with banks and card networks. One provider can supply both functions, which is why merchant dashboards sometimes present them as one service.
Every card payment starts with an amount and ends with records that can be matched to a payout. The core path stays consistent even when the provider combines several stages behind one interface.
The POS, website or payment application creates the order amount and transaction context. A usable request includes the merchant, location, currency, time, order reference, sales channel and transaction type.
An integrated POS sends the order total directly to the payment component. A standalone terminal requires the cashier to enter the amount, so the merchant must later match terminal transactions against POS sales.
The order reference matters as much as the amount. Two customers can spend the same amount within one minute. A stable order ID connects the sale, payment attempt, receipt and fulfilment record without relying on guesswork.
The customer presents a chip card, contactless card, mobile wallet or online credential. The acceptance method changes how payment data enters the system, not which financial parties approve and settle the transaction.
A fingerprint or face check on a phone unlocks the wallet credential. The issuer still decides whether to approve the purchase.
Authentication answers whether the person or credential satisfies the required verification rule. PIN entry, wallet verification and online authentication are examples.
Authentication does not move money and does not replace authorization. A customer can pass a verification check and still receive a decline because the issuer rejects the amount, account status or risk conditions.
Authorization sends the amount and payment data from the merchant side to the issuer and returns an approval or decline. The processor and acquirer route the request through the card network.
Mastercard’s description of the card authorization flow follows the request from the merchant’s POS to the acquirer, through the network to the issuer, and back with the response.
An approval means the issuer accepted the request under the current account and risk conditions. The approval does not mean the merchant has received cash in its bank account.
A decline means the merchant should request another payment method. Staff should not repeatedly retry the same payment without understanding the response because repeated attempts can create customer confusion or additional risk controls.
Capture tells the payment provider to submit the authorized amount for completion. Immediate retail sales often capture automatically. Hotels, bars, rentals and online fulfilment workflows can authorize first and capture later.
The captured amount can match the authorization or follow provider rules for an adjusted final amount. The merchant’s operating policy must define when capture occurs and what happens when the final amount changes.
Clearing exchanges completed transaction details, settlement resolves obligations among financial participants, and payout sends eligible net funds to the merchant. These are connected stages, not three names for the same event.
The merchant’s provider groups transactions according to its processing and funding schedule. Fees, refunds, reserves, chargebacks and other adjustments can change the final deposit.
A merchant needs an active acceptance relationship, not just a card reader. An acquirer, processor or payment provider verifies the business, enables supported payment channels and connects approved hardware or software to the merchant account.
Merchant setup defines:
The full guide to accepting credit card payments covers merchant applications, equipment preparation, transaction testing and first-payout verification.
Buying used payment hardware does not activate processing. The provider must provision the terminal or application for the correct merchant, account and location. A device with a card slot and contactless reader remains unusable when the chosen processor does not support its software, keys or configuration.
A fictional $100 sale shows how one customer action creates several merchant records. The example excludes taxes and provider fees so each state stays clear.
| Stage | Main record | Merchant state | Bank deposit received? |
|---|---|---|---|
| Order created | Order ID and $100 total | Awaiting payment | No |
| Credential presented | Card, wallet or token data | Reading payment | No |
| Authentication | PIN, wallet or online verification result | Processing | No |
| Authorization | $100 request and issuer response | Approved | No |
| Capture | Final $100 submission instruction | Captured | No |
| Clearing | Completed transaction record | Submitted | No |
| Network settlement | Issuer-acquirer obligation resolved | Settled in network records | Not necessarily |
| Merchant payout | Eligible net amount sent to the merchant bank | Paid out | Yes |
The merchant should never reconcile a payment by amount alone. The order ID links the sale to the POS. The processor transaction ID identifies the authorization and capture. A batch or clearing reference groups submitted transactions. The payout reference links the net transfer to the bank deposit.
The customer can also see more than one temporary balance state. An authorization can appear as pending before the final transaction posts. A reversal can release an unused authorization, while a later refund creates a separate return transaction.
In-person and online payments use the same core financial roles but collect and verify credentials differently. Both channels still require authorization, completed records and merchant funding.
| Area | In-person payment | Online payment |
|---|---|---|
| Credential entry | Chip, contactless card or wallet at a terminal | Payment page, wallet or embedded checkout |
| Customer verification | PIN, terminal rules or wallet verification | Online authentication and risk controls |
| Integration | POS-to-terminal connection or standalone terminal | Gateway, API, hosted page or e-commerce plugin |
| Main operational risk | Amount mismatch, terminal timeout or connectivity loss | Duplicate requests, browser interruption or delayed system updates |
An in-person terminal handles the physical card interaction. An integrated setup sends the order total from the POS and returns the result to the same order. A standalone terminal processes the payment separately, which increases reconciliation work.
An online payment page replaces the physical terminal interaction. The website creates the order, the gateway secures the credential, and the processor sends the authorization request. The site must also handle delayed notifications because closing a browser does not cancel a request already received by the provider.
Payment technology protects credentials, routes messages and synchronizes transaction states. Each component solves a defined problem.
None of these tools replaces the full processing chain. A token represents a credential, not money. EMV supports the card-terminal exchange, not merchant payout. A fraud score informs a decision but does not perform clearing or settlement.
Reliable integrations also use stable request identifiers and controlled retry logic. A timeout means the merchant interface lacks a final result; it does not prove the transaction failed.
Authorization happens during checkout, while clearing, settlement and merchant payout follow later schedules. This timing difference is normal and should be visible in merchant reports.
Mastercard describes switching and clearing as the exchange of transaction details between acquirers and issuers for posting and settlement reconciliation. Clearing establishes the records used to calculate financial obligations; settlement handles the corresponding positions.
Merchant payout is a separate provider-to-bank transfer. The deposit can combine many sales and subtract refunds, fees, reserves or chargebacks. A $1,000 payout therefore does not need to match one $1,000 receipt.
Three timestamps describe the funding path. Authorization time records the checkout decision, settlement time records the financial processing stage, and payout time records when the provider sends eligible funds toward the merchant’s bank. The bank can post the credit later than the provider initiates it.
A useful payout report identifies the included transaction IDs, gross sales, refunds, fees, reserves, net payout, payout reference and expected bank date. These fields let the merchant rebuild the deposit instead of comparing one daily sales total with one bank value.
The detailed POS settlement process explains how authorization time, network settlement and bank posting create separate timestamps.
Provider dashboards use different labels, so merchants should map each provider status to an internal meaning. “Approved,” “captured,” “settled” and “paid out” should never collapse into one generic “success” state.
A merchant should check the original transaction state before retrying a failed or uncertain payment. Blind retries create duplicate charges and disconnected records.
| Event | Meaning | Correct action |
|---|---|---|
| Decline | The issuer or processing system rejected the request | Request another payment method |
| Timeout | The merchant did not receive a final response in time | Query the original transaction before retrying |
| Duplicate | Two financial records exist for one intended order | Stop retries and follow the provider’s correction process |
| Reversal | An authorization or incomplete transaction was released or cancelled | Confirm the original state and customer balance |
| Refund | A completed payment received a separate return transaction | Preserve both the sale and refund records |
| Outage | A required terminal, gateway or processor service is unavailable | Use an approved continuity method or pause card acceptance |
A void and a refund change different processing states. A void cancels a transaction before the provider’s supported completion or cutoff point. A refund returns value after the sale has progressed further. The guide to POS void versus refund explains how timing changes the receipt, customer balance and reconciliation record.
Payment continuity plans should define approved offline functions, alternate lanes, supported tender types and escalation contacts. Staff should never record card details outside the approved payment system as an improvised workaround.
Reconciliation connects the sales record, processor transaction, payout report and bank deposit. Each layer answers a different question:
A reliable chain follows this sequence:
Order ID → processor transaction ID → batch or clearing reference → payout ID → bank deposit
Daily POS sales rarely equal the next deposit exactly. Funding cutoffs, weekends, fees, refunds, reserves and grouped payouts create timing and value differences.
Named exception categories make reconciliation actionable. An unmatched sale, missing capture, duplicate payment, unrecorded refund and payout adjustment each need a different owner and response. A single “difference” category hides the cause.
Payment processing cost combines network fees, provider pricing and merchant technology costs. A statement can include interchange, network fees, processor markup, fixed transaction charges, gateway fees, cross-border charges, chargeback fees, monthly subscriptions and equipment costs.
Hardware cost is not a card-network fee, even when one provider bundles both into a single commercial package.
The effective cost depends on the merchant’s real transaction mix:
Merchants should compare total annual cost with their own data. A low percentage paired with a high fixed fee performs poorly for small transactions, while a monthly plan loses value when volume stays low.
Provider selection should also cover market support, terminal compatibility, payout reporting, status clarity, refund tools, support escalation and contract exit terms. A low headline rate does not compensate for missing transaction references or unreliable payout reports.
The issuing bank approves or declines the authorization request. Merchant and processor risk controls can block a transaction earlier, but the issuer controls the card-account decision.
A gateway secures and transmits payment information from a website or application, while a processor routes and records transaction messages. One provider can offer both services.
No. Approval confirms the issuer’s authorization response. Capture, clearing, settlement and merchant payout still follow.
Authorization is the issuer’s checkout decision; settlement resolves financial obligations after completed transaction records enter clearing. Merchant payout is the later credit to the business bank account.
Authorization returns during checkout, while clearing, settlement and payout follow provider and banking schedules. Funding cutoffs, weekends, reserves and account status affect the final bank date.
The merchant should query the original transaction before retrying. A timeout shows that the interface lacks a final response; it does not prove that the processor rejected the payment.
Both channels use merchant, acquiring, network and issuing functions, but they collect and authenticate credentials differently. Stores use terminals; online checkouts use gateways, payment pages and card-not-present controls.
Payment processing is a sequence of messages, decisions and financial records rather than one instant transfer. Authorization decides whether checkout proceeds. Capture confirms the submitted amount. Clearing exchanges completed records. Settlement resolves institutional obligations. Merchant payout sends the eligible net amount to the business bank account.
Merchants gain control by linking every order to a transaction ID, payout reference and bank deposit. That record chain explains approved sales, failed attempts, refunds, adjustments and funding without guessing where the money went.






 Home
 How to Accept Credit Card Payments: A Step-by-Step Setup Guide for Small Businesses?

